Serving homeowners throughout Washington State
Stay in the home you love, with more freedom each month.
A HECM mortgage may let homeowners 62+ use part of their home equity, with no monthly mortgage payment required. You keep ownership and keep paying taxes, insurance and upkeep. I'll explain it all in plain words.
HECM mortgage guidance for Seattle, Bellevue, Kirkland, Tacoma, Spokane, Everett and Vancouver homeowners and communities across Washington.
- ✓ Lending since 1993
- ✓ Licensed throughout Washington
- ✓ 5.0 ★ on Zillow
In plain words
What is a HECM mortgage?
A HECM mortgage (Home Equity Conversion Mortgage) is an FHA-insured home loan for people 62 and older. Instead of you paying the lender each month, you can receive money from your home's equity: as a lump sum, monthly amounts, a line of credit, or a mix.
You still own your home. The loan is usually repaid when the last borrower moves out, sells, or passes away, often from the sale of the home. With a HECM, you or your heirs will never owe more than the home is worth.
Why families consider it
How a HECM mortgage may help
No monthly mortgage payment required
Pay off an existing mortgage and free up monthly cash flow. You still pay property taxes, insurance and HOA dues, and maintain the home.
Flexible ways to receive funds
Lump sum, monthly payments, a line of credit, or a combination, depending on the program you choose.
Keep ownership of your home
Your name stays on the title. Live there as long as you meet the loan terms.
Non-recourse protection
With a HECM, you or your heirs never owe more than the home is worth when it's sold.
Buy a home that fits
A HECM for Purchase can help you right-size into a home that suits this chapter of life.
Options for higher-value homes
Above the FHA limit? A jumbo home equity conversion loan may be worth comparing.
About taxes: loan proceeds generally aren't treated as income, but please consult a tax advisor about your situation.
Who qualifies
Is this a fit for you?
- Age 62 or older (youngest borrower, for a HECM; some jumbo programs may have different age requirements; ask Jason)
- Your primary residence: a single-family home, 2–4 unit home you live in, or an approved condo or manufactured home
- Enough equity: you own your home outright or have a meaningful amount paid down
- Able to keep up property taxes, insurance, HOA dues and upkeep (lenders review this)
- HUD-approved counseling completed before applying for a HECM
Educational estimate
See if you may qualify & get a rough range
Three quick answers. No name, no credit check, nothing is saved.
Your estimate will appear here.
Estimate only for educational purposes, not a loan offer or commitment. Actual amounts depend on age, interest rates, home value, fees and lender approval. Uses HUD's official HECM principal limit factors (HUD PLF tables, effective for case numbers on or after 10/2/2017), based on HUD expected-rate assumptions, and a 2026 FHA HECM maximum claim amount of $1,249,125 (HUD). Subtracts an estimated 2% FHA upfront mortgage insurance premium, an estimated origination fee plus about $4,000 in other closing costs, and your mortgage balance; actual costs vary. Your actual figures depend on current rates and a full quote. No rates are quoted.
Two kinds of HECM mortgages
FHA HECM, jumbo home equity conversion loan, or a second home equity conversion loan?
FHA HECM
The most common HECM mortgage, insured by the FHA. For 2026, it's based on home values up to the FHA maximum claim amount of $1,249,125 (HUD). Includes non-recourse protection and required HUD counseling.
Jumbo (proprietary) home equity conversion loan
Private programs for higher-value homes, which are common around Seattle and the Eastside. They may allow access to more equity on homes above the FHA limit, and some programs may accept more condos. Some jumbo programs may have different age requirements; ask Jason. Terms vary by program. Learn more →
Stand-alone second home equity conversion loan
Like your current mortgage rate? A stand-alone second home equity conversion loan may let you keep your existing first mortgage and access equity behind it, with no monthly payment required on the second. Program guidelines vary. Learn more →
As a broker with NEXA Lending, I can compare programs from multiple lenders so we can look at what fits you.
Clearing things up
Myths vs. facts
Myth: “The bank owns my home.”
Fact: You keep the title and ownership. The lender holds a lien, like any mortgage.
Myth: “My kids will be stuck with debt.”
Fact: With a HECM, heirs never owe more than the home is worth. They can keep it, sell it, or walk away.
Myth: “I'll never have to pay anything.”
Fact: No monthly mortgage payment is required, but taxes, insurance, HOA dues and upkeep continue.
Myth: “I have to own my home free and clear.”
Fact: Many people use a HECM mortgage to pay off their existing mortgage.
30+ years of experience, working for you
My simple 4-step process
I've been helping Washington homeowners since 1993. My job is to make this calm, clear and easy, and to answer every question before you decide anything.
- 1
A free, friendly conversation
We talk about your goals, your home and your questions. No pressure and no obligation. Invite your family if you like.
- 2
HUD-approved counseling
Before applying for a HECM you'll meet with an independent HUD-approved counselor. It's usually a phone call of about 30 minutes, and everyone on the title takes part. I'll give you a list of counselors and explain what to expect.
- 3
I handle the paperwork
I gather documents, order the appraisal and coordinate with the lender, title and escrow. I'll keep you updated in plain words at every step.
- 4
Close and live comfortably
We review every figure together before you sign. After closing, I'm still just a phone call away.
Family welcome
Bring your son, daughter or advisor
This is a family decision, and I treat it that way. Adult children, trusted friends, financial planners and attorneys are always welcome on our calls. I'll send clear written summaries so everyone sees the same numbers, and I'll never rush anyone.
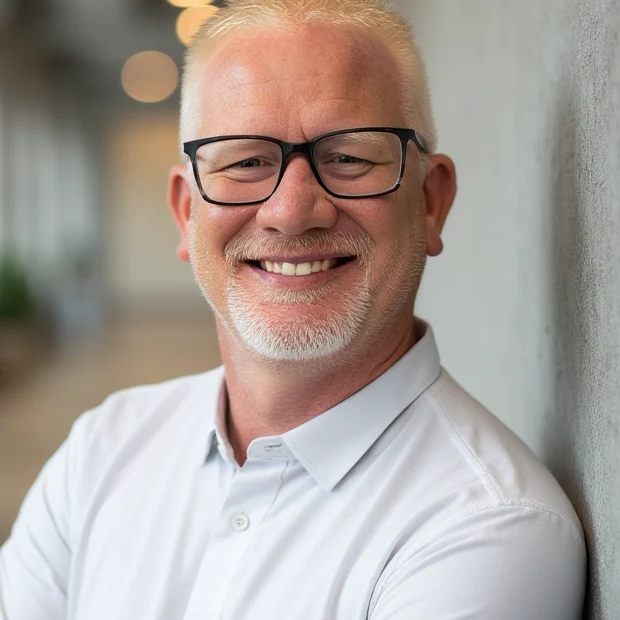
About me
Hi, I'm Jason Gray.
I've been in home lending since 1993, and today I'm Branch Manager with NEXA Lending in Kirkland.
Over more than 30 years I've learned that people don't want a sales pitch. They want straight answers and someone who will pick up the phone. That's what I offer. I serve homeowners throughout Washington State, including Seattle, Bellevue, Kirkland, Tacoma, Spokane, Everett and Vancouver, and as a broker I can compare HECM and jumbo home equity conversion options from multiple lenders.
Whether a HECM mortgage turns out to be right for you or not, you'll leave our conversation understanding your choices.
Jason Scott Gray · NMLS 118354 · NEXA Lending NMLS 1660690
1524 Market Street, Suite 103, Kirkland, WA 98033 · Map
In clients' words
What clients say
5.0 stars from 21 reviews on Zillow. Reviews shown verbatim from Zillow; they relate to Jason's home lending and some predate NEXA Lending.
“Jason went above and beyond to get us into a house. Lots of lenders wouldn't have been able to help , but Jason's experience and diligence made it possible for us. Highly recommended.”
“Jason was very professional and sharp during the whole mortgage process. He helped me and my family find a mortgage and then go through the entire procedure painlessly. Jason's support was essential for us, as he replied very quickly, including during the weekend. I would highly recommend him and his team!”
“We had a great experience with Jason. He was open and forthright from beginning to end, and responded to questions and concerns quickly. He maintained a high standard of contact throughout the process and lived up to every commitment he made. He and his team provided service that exceeded my expectations. I have and will continue to recommend Jason Gray.”
Common questions
Frequently asked questions
What is a HECM mortgage?
Do I still own my home?
Do I have to make monthly payments?
Who qualifies?
What happens to my home when I pass away? Will my children inherit it?
Is the money taxable? Will it affect Social Security or Medicare?
Washington State only
Areas we serve
I serve homeowners throughout Washington State, from my Kirkland office to every corner of the state.
- Seattle
- Kirkland
- Bellevue
- Redmond
- Tacoma
- Everett
- Olympia
- Vancouver, WA
- Bellingham
- Spokane
- Yakima
- Tri-Cities
- Moses Lake
- Wenatchee
- Chehalis
Don't see your town? If your home is in Washington, I can help. Call 425-260-3482.
No pressure. No obligation.
Request a free call
Tell me the best time to reach you and I'll call you myself. We'll just talk. Family members are welcome to join.
Prefer email? jsgray@nexalending.com